Home Loan Guide for First-Time Buyers in India 2026: Rates, Eligibility & Tips
For most Indian home buyers, a home loan is the cornerstone of their property purchase. With hundreds of lenders, variable interest rates, and evolving governme...
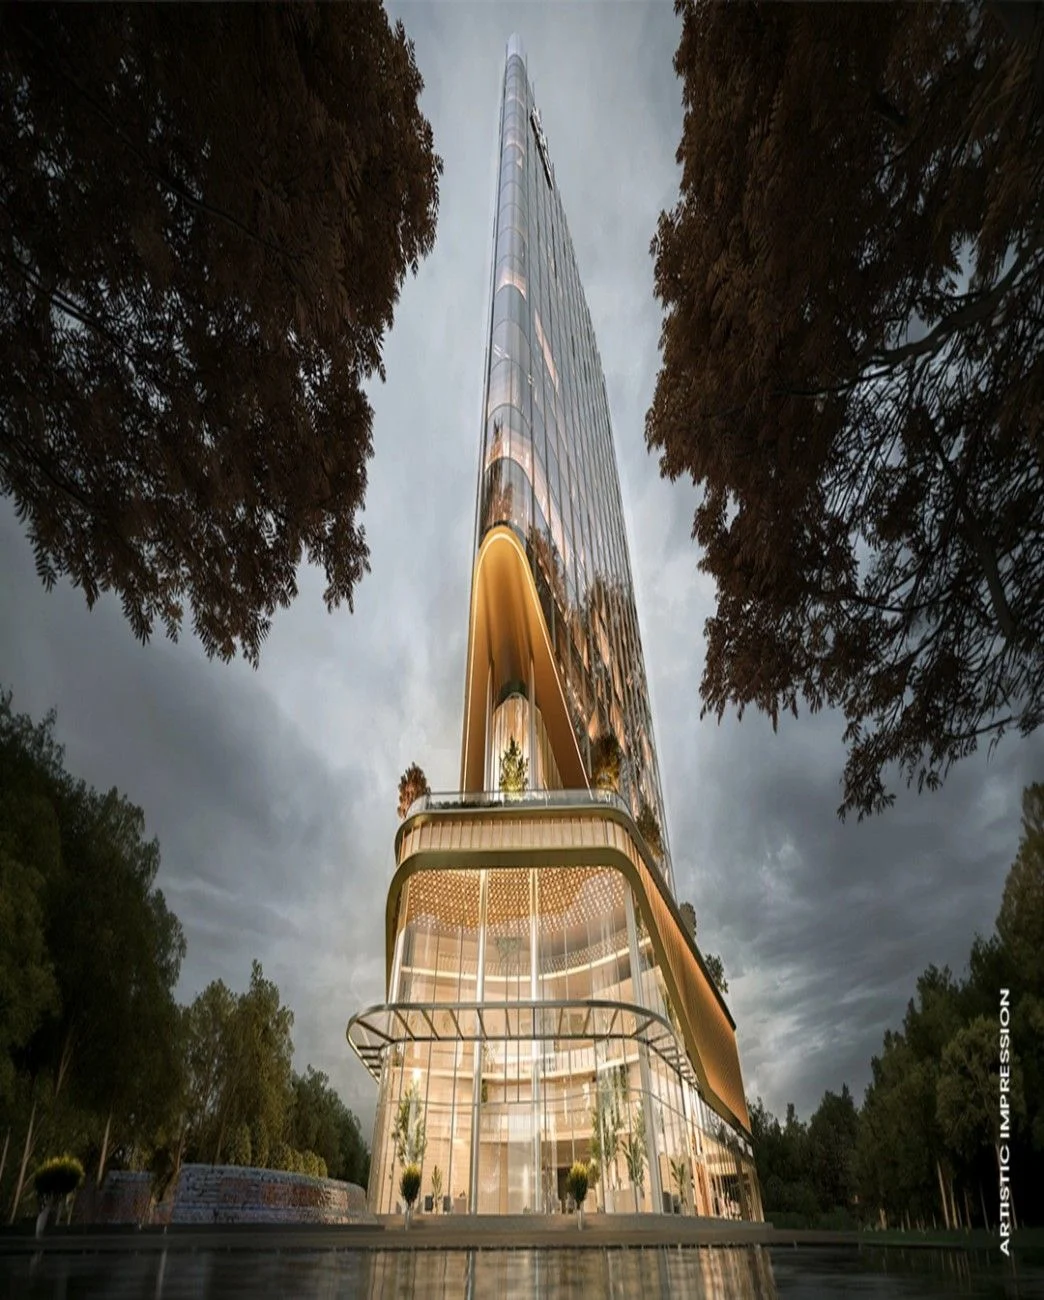 Commercial
check_circle 30-Yr Clear Title Dossier
M3M CFC (Capital Finance Center)
M3M CFC Sector 113 Gurugram – Premium Grade A Office Spaces, Retail & Commercial Hub M3M Capital Financial Centre (M3M CFC) is a premium Grade...
 Commercial
check_circle 30-Yr Clear Title Dossier
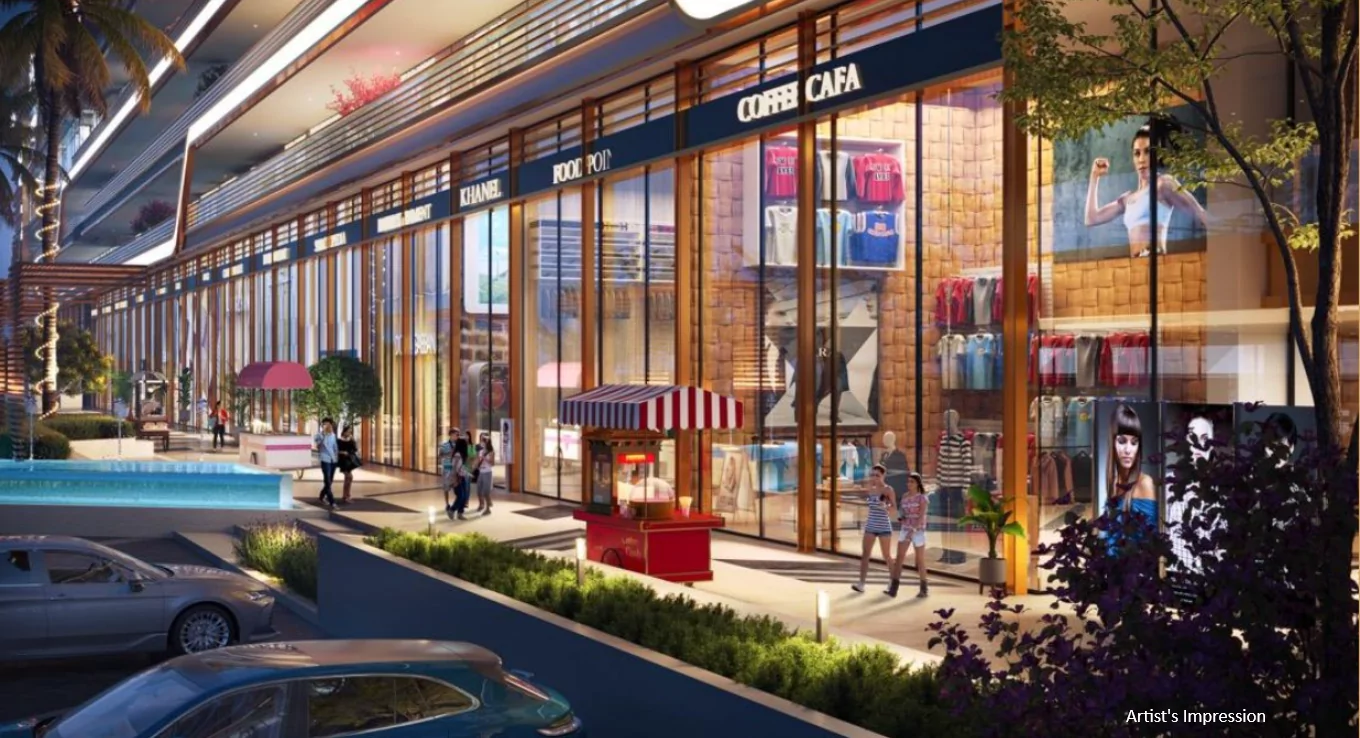
M3M The Line, Sector 72, Noida
M3M The Line Sector 72 Noida – Premium Retail Shops, Pentsuites & Studio Apartments M3M The Line is a mixed-use commercial development located...
 Commercial
check_circle 30-Yr Clear Title Dossier
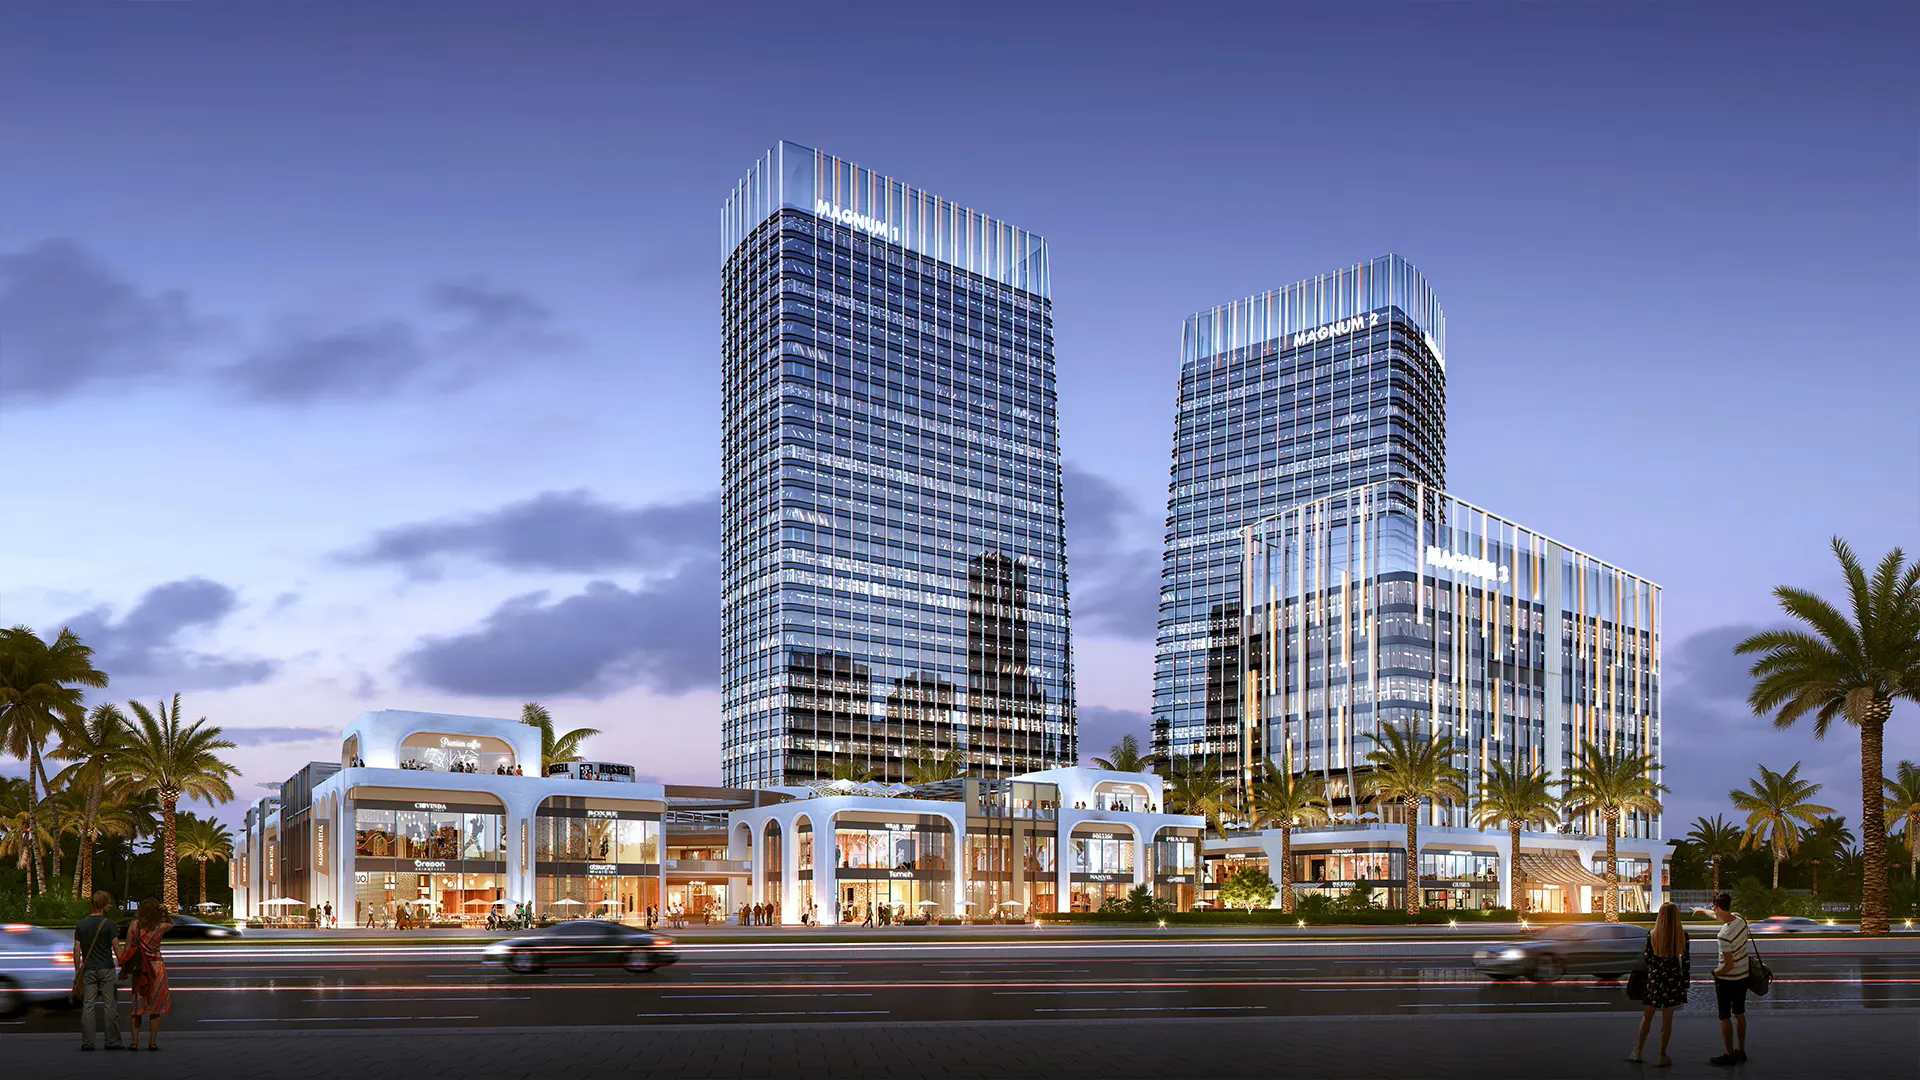
Magnum Business District
Magnum Business District Sector 74 Gurugram – Premium Office Spaces on SPR Magnum Business District (MBD74) is a premium commercial development in...
Home Loan Guide for First-Time Buyers in India 2026: Rates, Eligibility & Tips
Executive Brief: What You Must Remember
Mandatory 30-Year Mother Deed Trace: Never stop at the seller's immediate purchase deed. A missing link in succession over three decades leaves room for ancestral co-sharer litigations.
Form 15 vs. Form 16 EC Discrepancy: Form 15 lists recorded registered mortgages and leases; Form 16 explicitly certifies "Nil Encumbrance" for the queried time window. Always request Form 15 first.
Revenue Khata Does Not Prove Ownership: Tax assessment books (e.g., A-Khata, 7/12 Extract, Patta) denote tax assessment liability, not conclusive civil title recognized by courts.
Cross-Check the CERSAI Registry: Physical title deeds may be held in bank vaults under equitable mortgages not yet reflected in state sub-registrar books.
Home Loan Guide for First-Time Buyers in India 2026: Rates, Eligibility & Tips
For most Indian home buyers — whether purchasing a flat in Noida, an apartment in Gurugram, or a home in Lucknow — a home loan is the cornerstone of their property purchase. With hundreds of lenders, variable interest rates, and evolving government subsidy programmes, navigating the home loan landscape in 2026 can feel complex. This guide simplifies everything — from understanding your eligibility and comparing rates to maximising your PMAY benefit and managing EMIs effectively. Use our EMI Calculator to get started instantly.
Home Loan Eligibility: Key Criteria
Lenders in India assess your home loan eligibility based on several factors. Whether you are buying in Delhi NCR, Mumbai, or Lucknow, these criteria remain consistent across all major banks and NBFCs:
- Age: Minimum 21 years; maximum repayment age typically 65–70 years
- Income: Minimum ₹25,000–30,000 per month for salaried applicants
- Credit score: 750+ for best rates; 650 minimum for most lenders
- Employment: Minimum 2 years continuous employment for salaried — common for IT professionals in Noida and Gurugram; 3 years ITR for self-employed
- Loan-to-Value (LTV): Typically 75–90% of property value — calculate yours with our EMI Calculator
Home Loan Interest Rates in 2026
Home loan interest rates in India in 2026 are in the range of 8.35–9.5% per annum, depending on the lender, loan amount, and borrower profile. For a ₹60 lakh property in Noida or Faridabad, even a 0.5% rate difference saves ₹3–5 lakh over 20 years. Most major banks are on the repo-rate-linked EBLR system, meaning rates change with RBI policy decisions.
- SBI: Among the lowest rates — especially beneficial for government employees buying in Lucknow and Dwarka
- HDFC Bank and ICICI Bank: Competitive rates with fast processing — popular for Gurugram and Mumbai buyers
- LIC Housing Finance and PNB Housing: Good options for self-employed borrowers in Noida and Faridabad
- Tip: A co-applicant with a good credit score can improve your loan terms — and women co-applicants get lower stamp duty in Delhi NCR and Mumbai
PMAY Scheme: Government Interest Subsidy
Under the Pradhan Mantri Awas Yojana — Credit Linked Subsidy Scheme (PMAY-CLSS), eligible first-time home buyers across India — including in Lucknow, Faridabad, Noida, and Dwarka — can receive interest subsidies. Income groups are classified into EWS, LIG, MIG-I, and MIG-II categories, with subsidies up to ₹2.67 lakh available. Check your eligibility and apply through your bank before loan disbursement. Explore PMAY-eligible affordable housing listings on DirectoHome.
Home Loan Documentation Checklist
- Identity proof: Aadhaar, PAN card
- Address proof: Aadhaar, utility bill, passport
- Income documents: 3 months salary slips, 2 years ITR, bank statements (6 months)
- Property documents: Sale agreement, NOC from builder, approved plan, title documents — verify builder details on DirectoHome's verified listings
- Self-employed: CA-certified financials, business proof, GST returns
How to Compare and Choose the Right Lender
- Compare effective interest rates, not just headline rates
- Check prepayment and foreclosure terms — opt for zero-penalty floating rate loans
- Evaluate processing fees, legal charges, and technical evaluation fees
- Read reviews on customer service, especially post-disbursement support
- Use DirectoHome's EMI Calculator to compare monthly outflows for properties in Noida, Gurugram, Lucknow, and Mumbai
Tips to Maximise Your Home Loan Benefit
- Step-up EMI: Start with lower EMIs that increase as your income grows — ideal for young IT professionals in Noida and Gurugram
- Prepay when possible: Even ₹50,000–1 lakh annual prepayment can reduce tenure by 3–4 years — simulate on our EMI Calculator
- Choose shorter tenure if affordable: 15–20 years saves significant interest vs 30 years
- Tax benefits: Claim deductions under Section 80C (principal: up to ₹1.5 lakh) and Section 24B (interest: up to ₹2 lakh for self-occupied property) — applicable whether you buy in Dwarka, Faridabad, or Mumbai
- Compare rent vs buy: Use DirectoHome's Rent vs Buy tool to decide if now is the right time to take the loan
Conclusion
A home loan is a long-term financial commitment that deserves careful planning. Whether you are buying your first flat in Noida, an apartment in Gurugram, a home in Lucknow, or a property in Dwarka or Faridabad — understanding your eligibility, comparing lenders, leveraging PMAY benefits, and managing EMIs wisely will make your dream home a reality. Use DirectoHome's EMI Calculator and explore our home buying guides to simplify your journey.
EMI Calculator | Rent vs Buy | Affordable Housing | Home Buying Guides | Noida | Gurugram | Delhi NCR | Lucknow | Mumbai | Faridabad | Dwarka | Price Trends

DirectoHome Consumer Due Diligence Cell
Have questions about an ongoing property transaction? Our title scrutiny desk provides verified, unbiased legal assessments.